Annual flagship · October 2026
The AI-Factory Economy 2026
The Top-25 AI-factory operators, from neoclouds and converted miners to wholesale platforms, benchmarked on power, silicon, contracts and the debt calendar.
Compute Terminal Research · Data as of 23 October 2026 · 35-page print edition · 71 dated anchors
Key findings
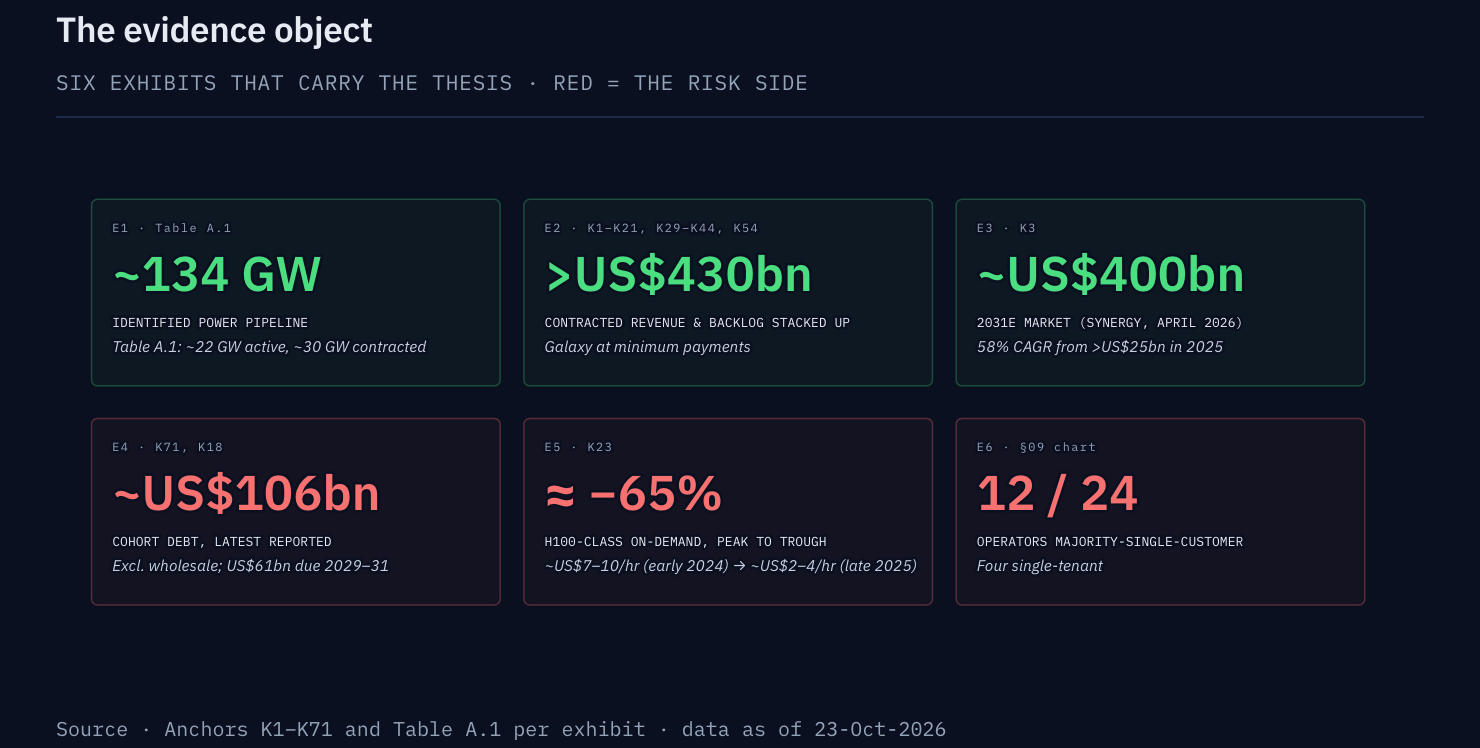
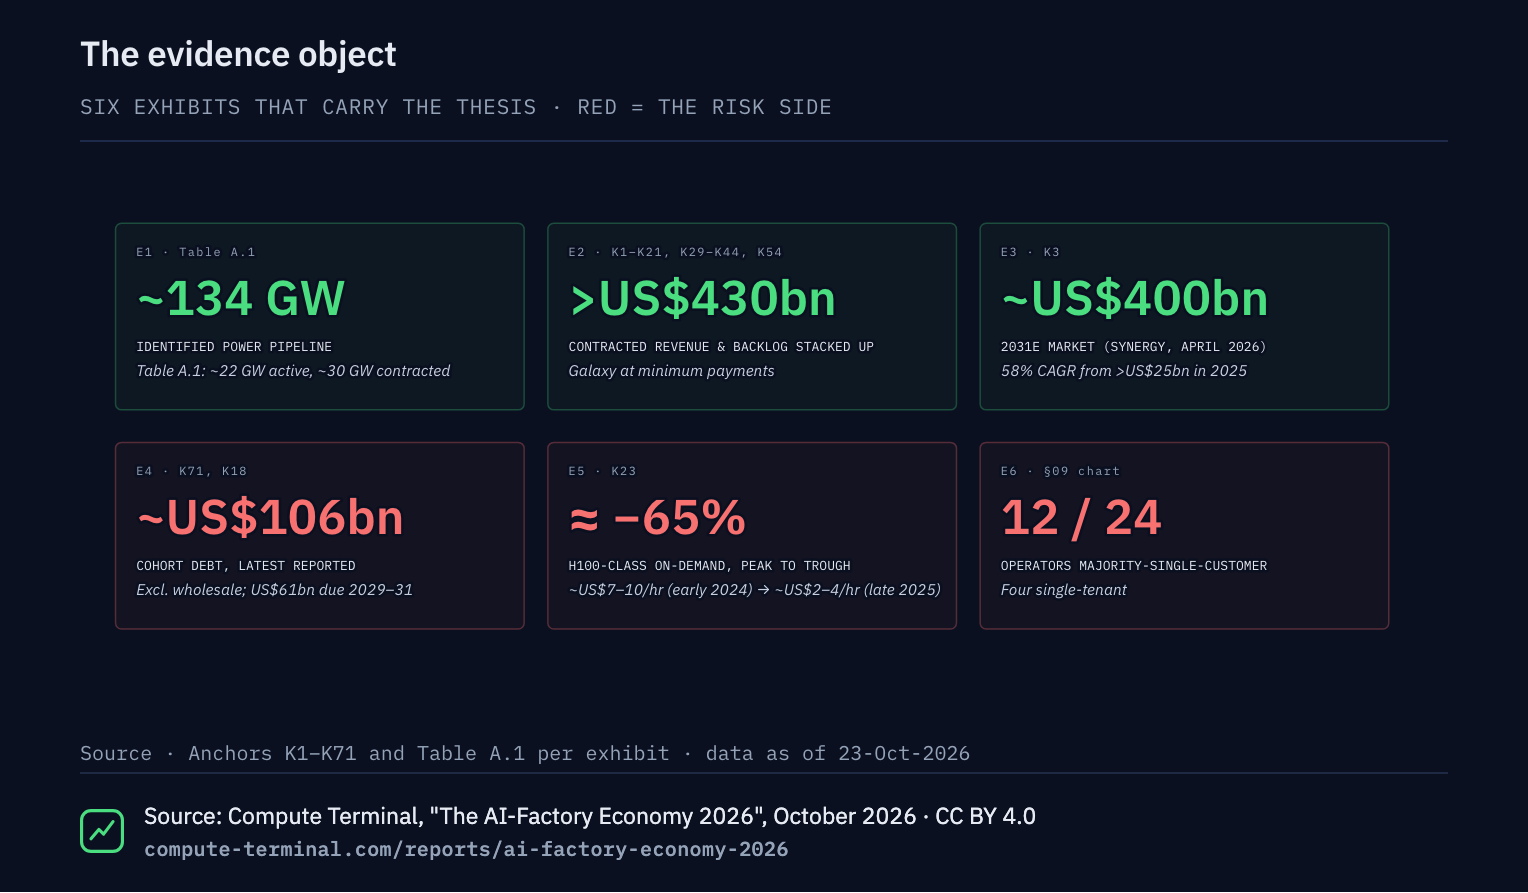
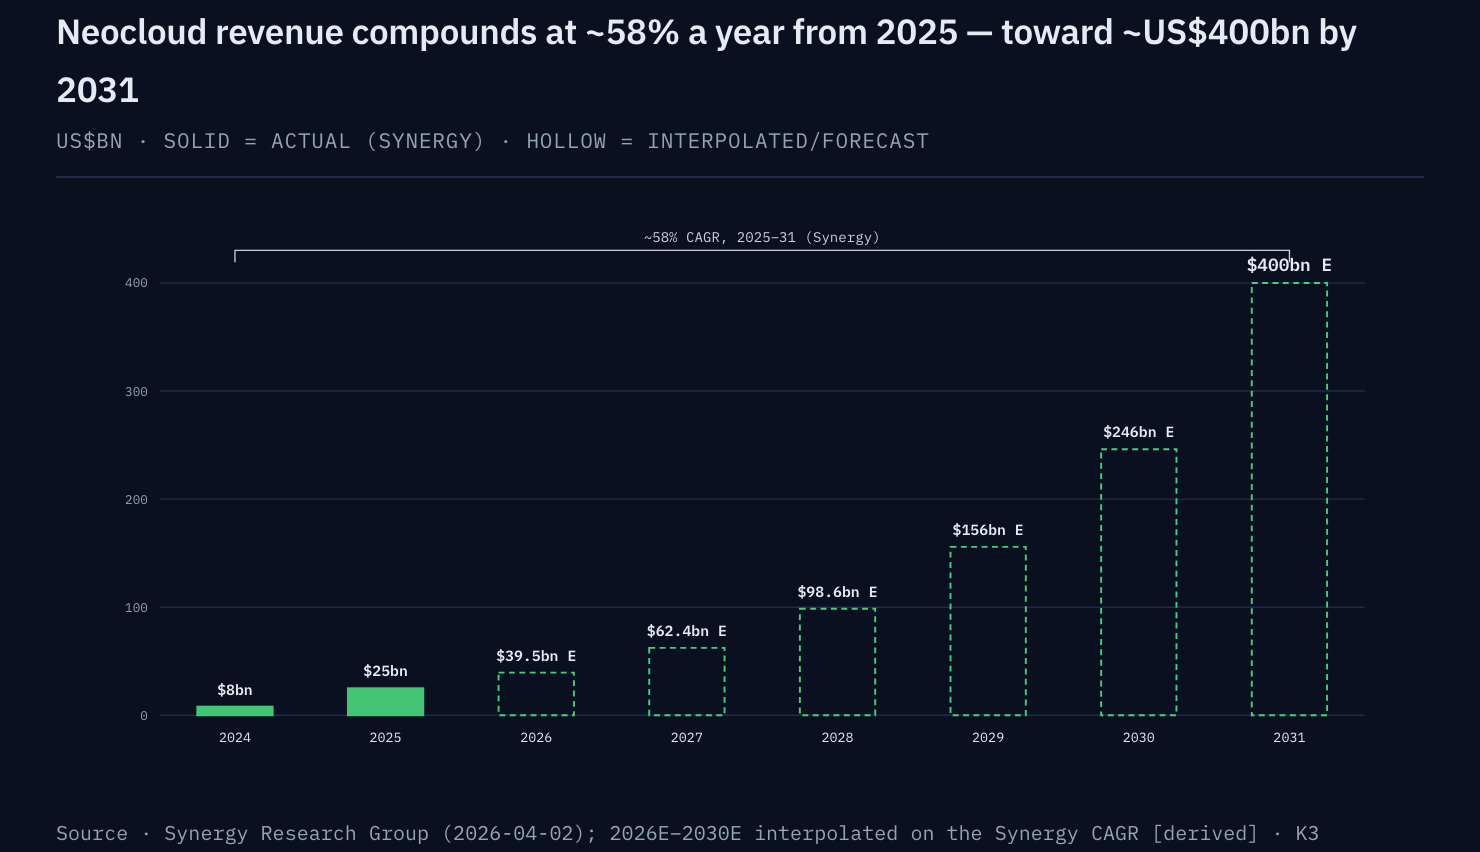
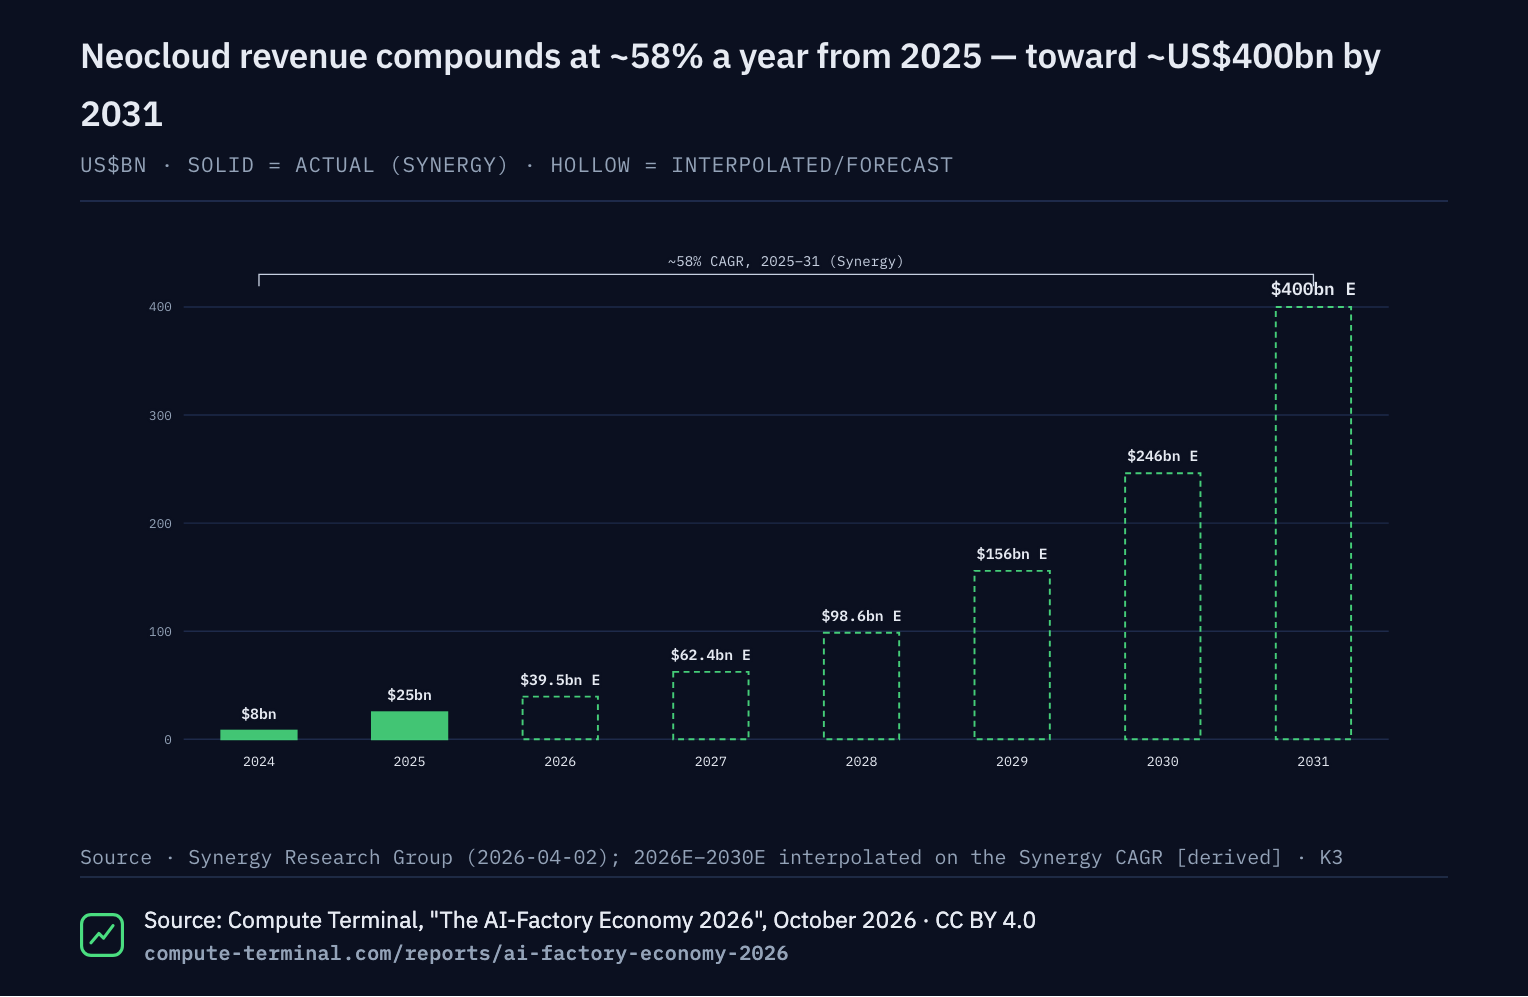
- Neocloud revenue compounds at about 58% a year, from more than US$25bn in 2025 to a Synergy-projected ~US$400bn in 2031.
- The Top-25 hold ~134GW of identified power pipeline, of which about 22GW is active and about 30GW contracted (Table A.1).
- Contracted revenue and backlog across the cohort exceed US$430bn, with Galaxy counted at its minimum payments.
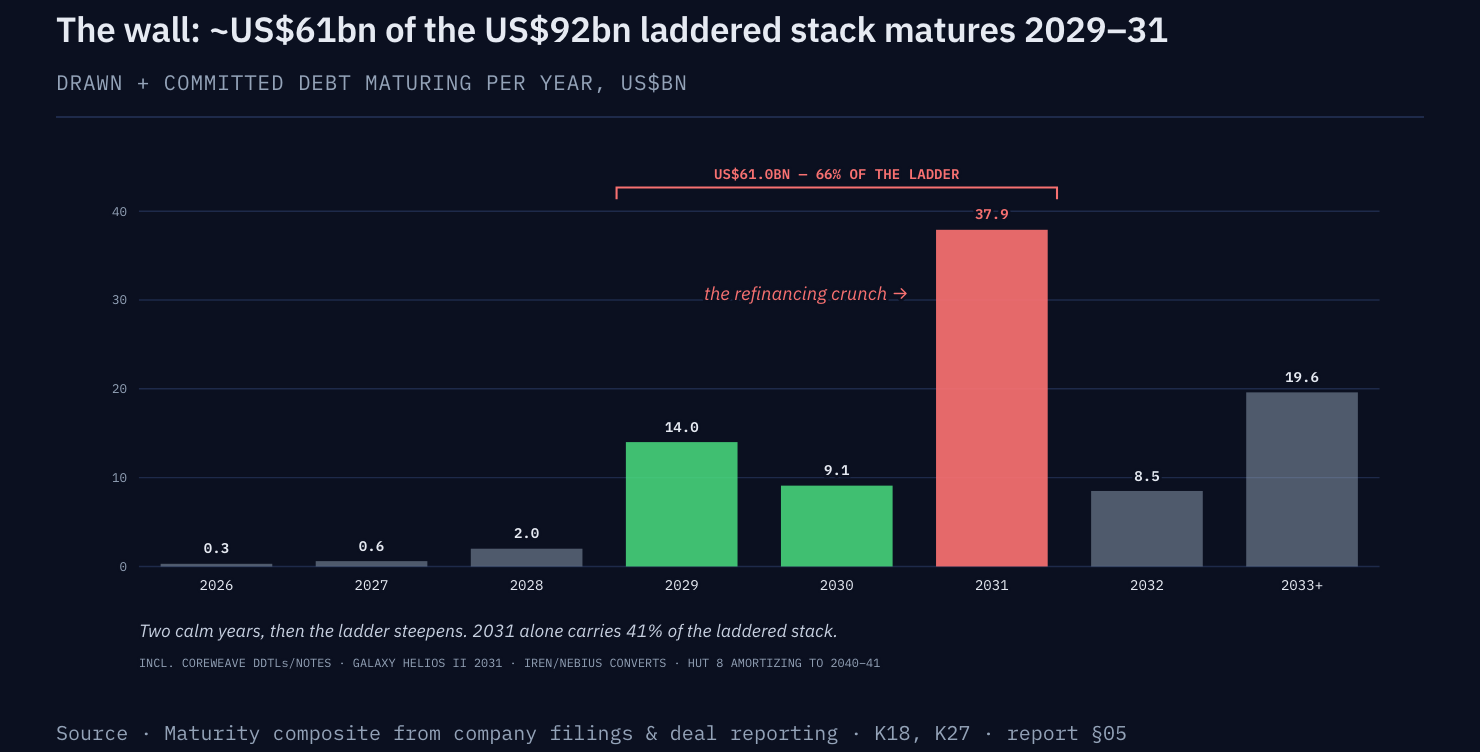
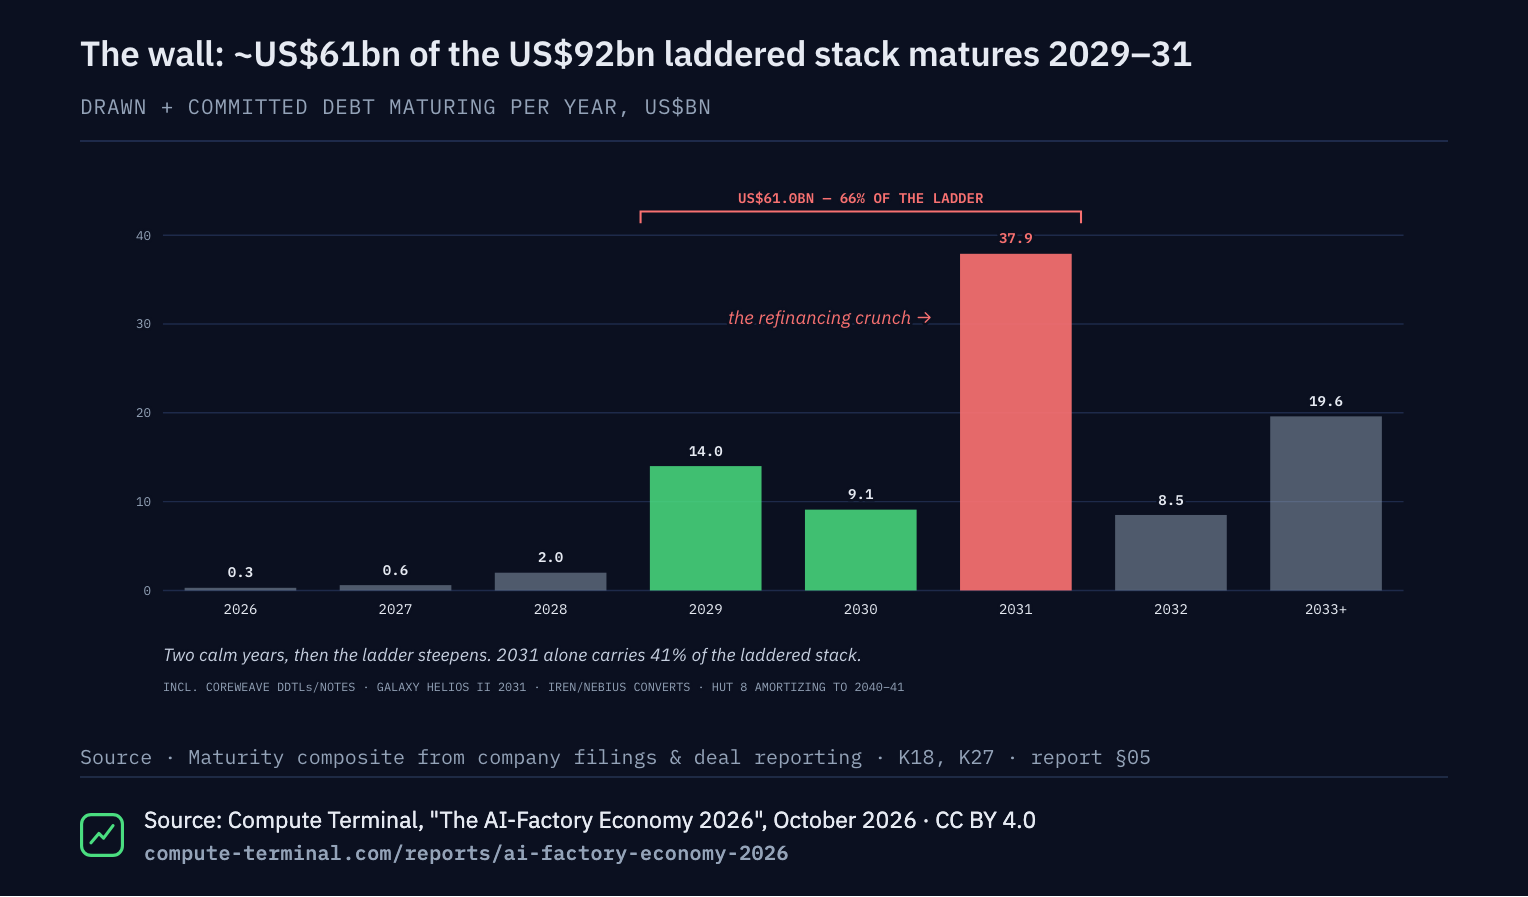
- Two calm years, then the calendar: only US$0.9bn of the cohort's US$92bn laddered debt falls due through 2027, while US$61bn (66%) matures in 2029–31 and 2031 alone carries 41%.
- On the report's eight 2031 winning factors (analyst judgement, not a rating), power-first Aligned and Vantage score 36 of 40 against fleet-first CoreWeave's 31.
Sources: Synergy Research Group (K3), company filings and deal reporting compiled in Table A.1 and the maturity composite (K18, K27), and the winning matrix (analyst scoring on company disclosures, K1–K21), as listed in the report's source register.
Exhibits
Free to reuse under CC BY 4.0 with the credit “Source: Compute Terminal” and a link back. The PNG and the embed carry both.
Free to reuse under CC BY 4.0 with the credit “Source: Compute Terminal” and a link back. The PNG and the embed carry both.
Free to reuse under CC BY 4.0 with the credit “Source: Compute Terminal” and a link back. The PNG and the embed carry both.
The Top-25
- CoreWeave
- Nebius
- Nscale
- Crusoe
- Lambda
- Fluidstack
- TensorWave
- Firmus
- IREN
- Applied Digital
- Cipher Digital
- TeraWulf
- Hut 8
- Bitdeer
- CleanSpark
- Galaxy
- Keel (ex-Bitfarms)
- Riot
- Fermi
- WhiteFiber
- Sharon AI
- Aligned
- Vantage
- Switch
- Khazna
Contents
Compute Open (summary edition)
- 00 Executive summary: five findings, one verdict
- 01 The market: the ramp, and the GPU hour deflating underneath it
- 02 The value stack: where the scarcity rent lives
- 03 The Top 25: three currencies of scale
Plus and Pro (full report)
- 04 The tape: 112 days that set the board, then shook it
- 05 The money: US$106bn against the calendar
- 06 Valuation: the band after the rout
- 07 The winning matrix: eight factors decide 2031
- 08 The captive fleet and the watchlist
- 09 Risk and gates: six gates, and the single-anchor book
- 10 Appendix: the master tables
- 11 Source register: K1–K71
Method and sources
Every figure in the report traces to a dated source in the K-register (K1–K71) or to the master tables. Company disclosures and regulatory data rank first; cross-checked journalism and broker research second; industry trackers, compilations and commentary third, always dated. Forecasts are marked as forecasts and analyst judgements as judgements. Prices are at the 22 October 2026 close. Corrections are logged at /corrections; how we research is at /methodology.
Questions
What is an AI-factory operator?
A company that builds or runs GPU datacentre capacity for AI training and inference and sells it as compute or as leased, powered space. The report covers three kinds: neoclouds, converters (mostly former bitcoin miners) and wholesale datacentre platforms.
Which companies are in the Top-25?
CoreWeave, Nebius, Nscale, Crusoe, Lambda, Fluidstack, TensorWave, Firmus, IREN, Applied Digital, Cipher Digital, TeraWulf, Hut 8, Bitdeer, CleanSpark, Galaxy, Keel (ex-Bitfarms), Riot, Fermi, WhiteFiber, Sharon AI, Aligned, Vantage, Switch and Khazna.
How are the operators scored?
On eight equally weighted factors for 2031, each scored 1–5 by our analysts on company disclosures, for a total out of 40 (analyst judgement, not a rating): power and grid position, contracts and duration, balance-sheet resilience, execution record, GPU and technology access, customer diversification, geographic and sovereign position, and cost-of-capital trajectory. Twenty of the 25 are scored in this edition; Bitdeer, CleanSpark, Firmus, WhiteFiber and Sharon AI will be scored in the next.
When does the sector's debt come due?
Of the US$92bn of laddered debt, only US$0.9bn falls due through 2027. US$61bn matures in 2029–31, and 2031 alone carries 41%. Reported cohort debt is about US$106bn, excluding wholesale platforms.
What changed in September and October 2026?
September's Fed hike and October's credit rout cut the mean EV/2027E sales multiple of the twelve listed names from 11.6× to 7.0×, and pulled the 2029 refinancing question into the present.
What is free and what needs Plus?
With a free Compute Open account you get the 10-page summary edition (sections 00–03). The full interactive report and the 35-page print edition are included in Compute Terminal Plus and Pro, with a 7-day trial on monthly Plus.
Is this investment advice?
No. It is impersonal, general research for information only, with no ratings and no price targets. See the conflicts and disclosure policy at /policy.
Impersonal, general research for professional market participants, including professional and sophisticated investors where receipt of such research is lawful. Not investment, procurement, engineering, legal or tax advice, and not a recommendation to buy or sell any security.
Research for information only. Not investment advice. Compute Terminal is subscriber-funded and publishes the same calls to every tier at the same time.
Compute Terminal Research. No ratings and no price targets. Conflicts and disclosure policy: /policy.
Compute Terminal Research · Published 31 Oct 2026 · Data as of 23 Oct 2026